Commercial finance jargon buster: 10 terms you need to know

One of the biggest misconceptions of first-time commercial property investors is simply thinking it is just like residential property investment, but on a larger scale.
In fact, the lending assessment can be very different, according to Mortgage Choice broker Bhav Jaswal.
Commercial property is increasingly attractive option following government changes to ban new self-managed super fund loans for residential property and understanding the financing is crucial to getting stated as a new investor.
“Many investors often focus heavily on the purchase price and rental yield, but there are other factors that can materially affect the investment,” Ms Jaswal explains.
These include the lease, tenant quality, outgoings, vacancy risk and the property’s ability to meet its debts.
Another rookie error is only looking at gross rental income. While a property may advertise an attractive rental return, investors should understand what expenses are payable by the landlord, and what can be recovered from the tenant, Ms Jaswal says.
Assuming a long lease automatically means a better investment is another common mistake she sees, when the quality of the tenant and terms of the lease are equally important.
Below are the key financial terms potential commercial property investors should know before diving in.
1. Yield (gross versus net)
Yield measures the income generated by a property compared to its market value or purchase price. It helps investors understand a property’s profitability.
Gross yield looks at the rent before property expenses. Net yield accounts for property expenses and running costs, providing investors a clearer picture.
“The distinction is important because a property can appear attractive based on its gross yield, but the actual income retained by the owner may be lower once outgoings are considered,” Ms Jaswal says.

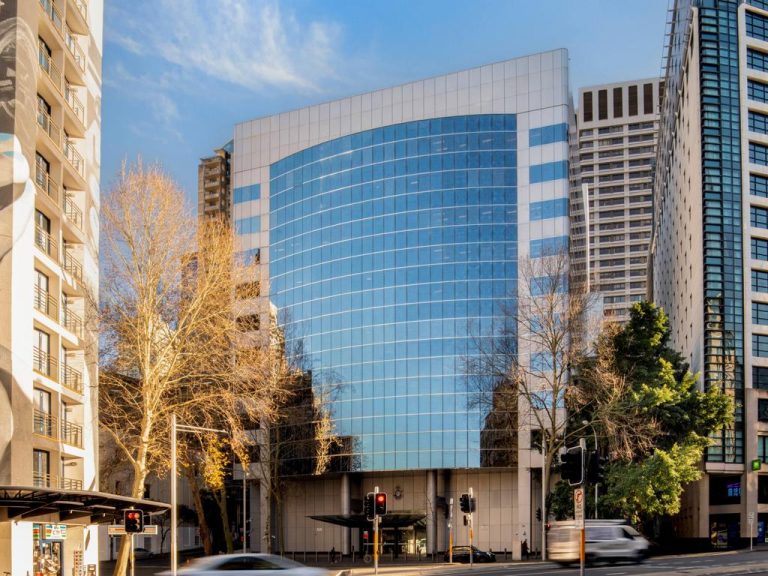
Gross yield captures rent before property expenses. Picture: Getty
“I always encourage investors to look beyond the headline yield and understand the property’s actual income and expenses.”
2. Outgoings
These are the property’s running costs, which can include council rates, water, insurance, land tax, strata fees, maintenance and repairs.
Who pays what depends heavily on the lease – some commercial leases allow the landlord to recover certain outgoings from the tenant, while others leave some or all costs with the landlord, Ms Jaswal explains.
“When assessing a property, buyers should review the lease carefully and understand exactly which outgoings are recoverable from the tenant and which remain the owner’s responsibility,” she says.
Landlord and tenant obligations are different in commercial investing. Picture: Getty
“This can have a significant impact on the property’s actual return.”
3. WALE (Weighted Average Lease Expiry)
WALE is the average time remaining on existing leases across the property. It is important as it gives investors an indication of the stability of the property’s rental income, Ms Jaswal says.
“Lenders also pay attention to it because the lease is often a key part of the property’s income and therefore its ability to support the loan.”
While a longer WALE can generally provide greater income certainty, longer isn’t automatically better, she says.
Lenders need to consider existing leases closely. Picture: Getty
Investors should also consider the quality of the tenant, rental amount, lease terms, options, market rent and what happens when the lease expires.
4. LVR (Loan-to-Value Ratio)
LVR is the amount borrowed compared with the property’s value. For example, for a property valued at $1 million with a $600,000 loan, the LVR is 60%.
The LVR can affect how much an investor can borrow, the deposit required and potentially the interest rate and overall cost of finance, Ms Jaswal states.
“Commercial LVRs can vary depending on the property, tenant, lease, location, borrower and lender. A lower LVR generally means the borrower is contributing more equity, which can reduce the lender’s risk and potentially provide access to better lending terms.”
5. Vacant possession
This is when a property is sold empty without an active tenant.
This can provide flexibility for an investor, because they can find a new tenant and potentially negotiate the lease themselves, Ms Jaswal says.
But it also means there may be no rental income immediately after settlement and this can be particularly important when applying for finance.
“With a tenanted property, the lender can often assess the existing lease and rental income as part of the overall assessment,” she says.
Circumstances are different when spaces are sold without tenants. Picture: Getty
“With vacant possession, the lender may take a different approach because there is no established rental income from a tenant.
Investors should consider both the opportunity and risk of potentially having a vacancy period, she says.
6. Going concern
This generally refers to property that is being sold with an active lease and tenant in place, rather than simply selling the underlying assets.
This is important, because when a commercial property is sold as a going concern, the GST treatment can be different, Ms Jaswal explains. But buyers should not assume a commercial property is automatically GST-free.

Not all spaces for lease have active tenants. Picture: Getty
“The contract, lease arrangements and transaction structure should be reviewed with the buyer’s accountant or tax adviser before proceeding,” she says.
7. Low-doc loan
This is a loan where the lender may require less financial documentation than a traditional loan application. This can be useful for self-employed buyers, business owners or investors who don’t have standard, up-to-date tax returns available.
Lenders still need enough information to understand the borrower’s financial position and assess risk. Trade-offs can include higher interest rates, lower LVRs, extra requirements or fewer lender options.
“It is important to compare the overall cost and suitability rather than choosing a loan simply because the documentation requirements are easier,” Ms Jaswal adds.
8. Debt Service Coverage Ratio (DSCR)
This measure asks whether the property’s income comfortably covers its debt obligations.
“Lenders use DSCR as one of the tools to assess whether the proposed debt is sustainable,” Ms Jaswal says.
“A stronger DSCR generally provides greater comfort to a lender, while a weaker ratio may result in lower borrowing capacity or additional conditions.”
It’s particularly relevant in commercial lending, she says, because the income generated by the property or business can be an important part of the lender’s assessment.
Property income needs to satisfy debt obligations. Picture: Getty
9. Capitalisation rate (cap rate)
This measure assesses the relationship between a commercial property’s net operating income and its value.
It helps investors understand the return the property is generating based on its income. For example, if a property generates $100,000 in net operating income and is valued at $2 million, the cap rate would be 5%.
“Cap rates can be useful when comparing commercial properties, but they should not be considered in isolation,” Ms Jaswal explains.
“Investors should also look at the tenant, lease, WALE, location, property condition, future rental growth and market conditions.”

Net operating income v value needs specific consideration. Picture: Getty
10. Interest Coverage Ratio (ICR)
This measures how comfortably the income can cover the interest expense on the debt. For investors and lenders, it indicates the property’s or business’s ability to service interest payments.
For example, if the relevant income is $200,000 and annual interest expense is $100,000, the ICR would be 2.0 times, Jaswal points out.
“Lenders may use ICR as part of their overall credit assessment, particularly where the property’s income is an important source of debt servicing.
“For a business owner, it can also be a useful measure of how much capacity the business has to manage its debt costs.”

Debt servicing is considered closely in credit assessments. Picture: Getty
Where residential and commercial property investment can differ
LVR: Investors familiar with residential lending may be used to relatively high LVRs, but commercial lending can be more conservative depending on the property and lender.
Rental income: In residential property, investors often focus on weekly rent. But in commercial property, the lease structure, rent reviews, outgoings, incentives and tenant obligations can have a much greater impact on the actual investment return.
Valuation: Commercial property valuations can be strongly influenced by the property’s income, lease terms, tenant and market evidence—not simply comparable sales. For example, two commercial properties may have a similar purchase price, but one could have a strong tenant on a long lease while the other has a short lease nearing expiry. From both an investment and lending perspective, those properties can carry very different levels of risk.

Mortgage Choice broker, Bhav Jaswal. Picture: Supplied
Consider the whole picture
Ms Jaswal advises first-time commercial investors to consider the whole picture rather than making decisions based on one number such as yield or purchase price.
“Don’t look at the advertised gross yield alone. Always check the outgoings and calculate the net yield to understand the property’s true income return,” she says.
For example, a commercial property that costs $1 million and generates $70,000 rent per year may have a gross yield of 7%, but if the owner pays $10,000 in expenses, the net income is $60,000 – a net yield of 6%.
“Understanding the property, lease, income, expenses and finance structure before committing can make a significant difference.”
The latest commercial property news
Get the latest news and insights straight to you.